
Nexo Loans - FAQ
1. What is the minimum and maximum fiat currency equivalent I can borrow in digital assets
The minimum loan amount you can withdraw is:
- 50 USD in stablecoins (USDT, USDC), or USDx*
- 500 USD for bank transfers
The maximum loan amount is 2,000,000 USD per day.
*Residents of Germany and Lithuania who register on or after June 30, 2026, receive credit disbursed to their Nexo account in USDx, with the option to subsequently convert to USDC.
2. What currencies are available for loan withdrawal
You can withdraw a Nexo loan in digital assets and receive the fiat currency equivalent of EUR, GBP, or USD via bank transfer. Alternatively, you can request a loan in stablecoins (USDT or USDC). The borrowed amount is added to your Savings Wallet, where you can exchange it for another cryptocurrency or FIATx if you wish. Regardless of the selected loan withdrawal currency, the total outstanding loan is displayed in xUSD on the Credit Line Repayment screen.
Notes:
- Loans in USDT are unavailable for residents of EEA countries.
- Residents of Germany and Lithuania who register on or after June 30, 2026, receive credit disbursed to their Nexo account in USDx, with the option to subsequently convert to USDC. Clients who registered before that date are unaffected.
3. How long does it take to get approved for a Nexo loan
Nexo crypto-backed loans are usually approved automatically, but due to KYC, AML, and other security requirements, it may take us up to 1 business day to approve your loan in some cases.
4. Do you perform credit checks and will a Nexo loan affect my credit score
One of the benefits of Nexo loans is the absence of credit checks. Furthermore, your loan data is not reported to credit agencies, meaning that your credit score will not be affected in any way.
5. How quickly will I receive the funds
The processing time of Nexo loans depends on the loan currency you select and the transfer type:
Bank transfers:
- Local transfer: Same/next business day
- International transfer: 1 to 5 business days
Stablecoins (USDT, USDC):
- Up to a few minutes to see the borrowed funds in your Savings Wallet.
Note: Our banking partner processes bank transfers on business days only.
6. What is the interest rate on my Nexo loan
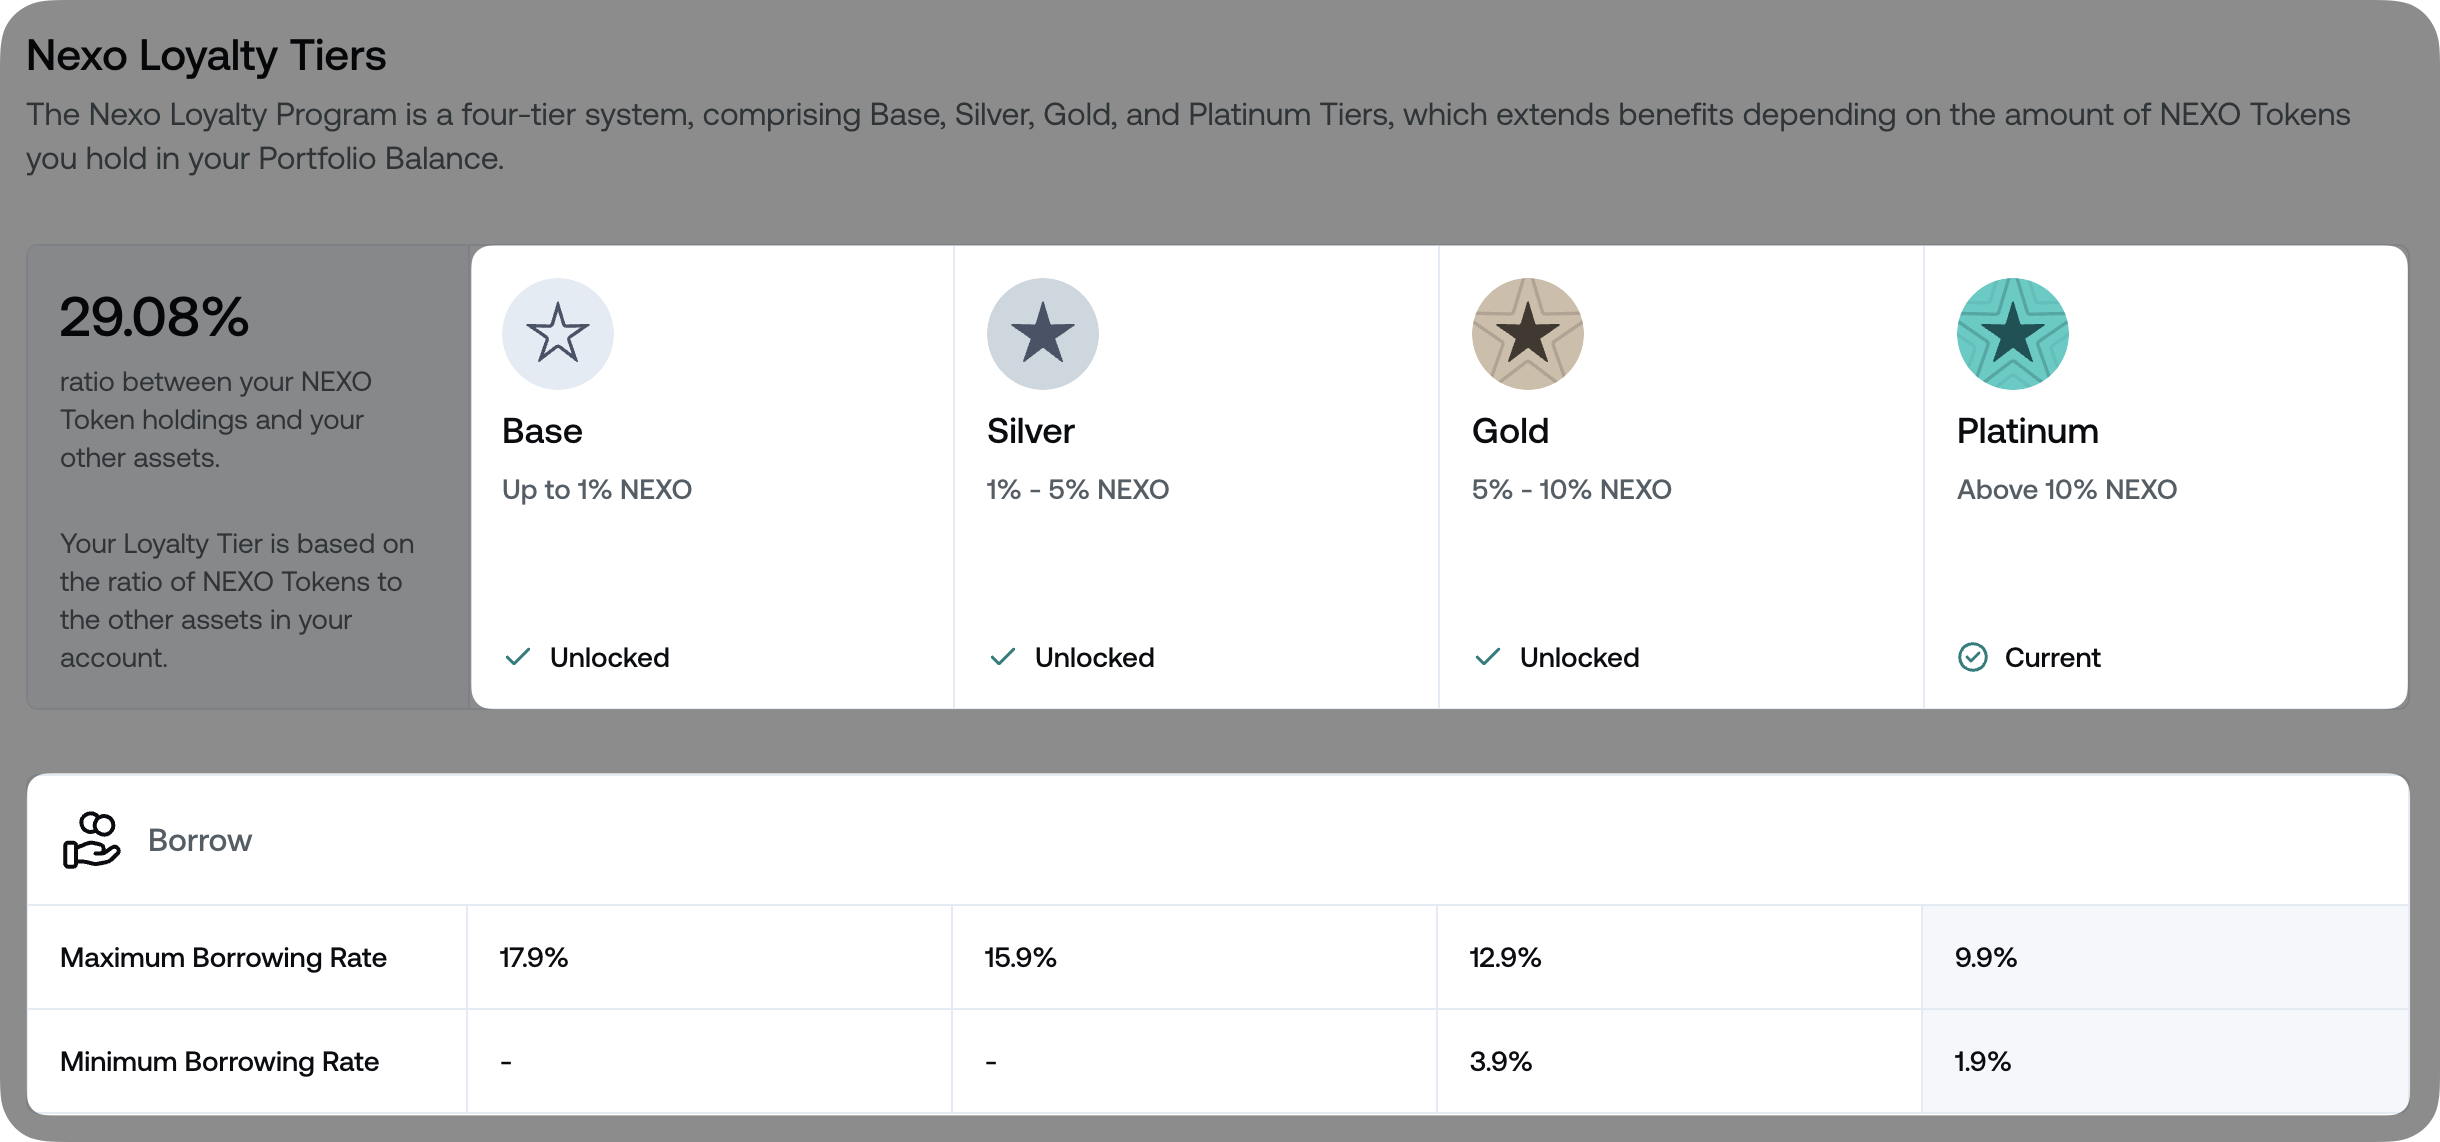
The loan interest rate is based on your Loyalty tier* and portfolio balance. Your Loyalty tier, in turn, is determined by the proportion of NEXO Tokens relative to the rest of your portfolio. Keep in mind the loan interest rate dynamically changes if your Loyalty tier shifts while you have an outstanding loan.
Below, we provide a detailed overview of the loan interest rates applicable to each scenario.
Portfolio balance below $5,000 (regardless of NEXO Tokens ratio) – 17.9%
Portfolio balance above $5,000 (Loyalty Program unlocked):
- Base (No NEXO Tokens) – 17.9%
- Silver (At least 1% NEXO Tokens against the rest of your portfolio) – 15.9%
- Gold (At least 5% NEXO Tokens against the rest of your portfolio) – 11.9% or 12.9%, depending on your jurisdiction
- Platinum (At least 10% NEXO Tokens against the rest of your portfolio) – 9.9%
* You need to maintain a portfolio balance of at least $5,000 in value to access our Loyalty Program and take advantage of lower interest rates on your loan. You can learn more in this article.
Example: To illustrate how Nexo loan interest works, let’s explore the following example in which you fall into the Platinum Loyalty Tier associated with a 9.9% annual interest rate:
Day 1: You borrow $100,000 from Nexo’s Credit Line.
Day 2: Daily interest in the amount of $27.50 is accrued. Your overall Nexo loan becomes $100,000 (principal) + $27.50 (daily interest day 2) = $100,027.50.
Day 3: Daily interest in the amount of $27.51 is accrued. Your overall Nexo loan becomes $100,000 (principal) + $27.50 (daily interest day 2) + $27.51 (daily interest day 3) = $100,055.01.
As you can see, the loan interest is calculated day by day, reflecting your Loyalty Tier. To demonstrate this, let us assume that on Day 4, you are in the Silver Loyalty Tier, where your annual interest rate is 15.9%:
Day 4: Daily interest in the amount of $44.19 is accrued. Your overall Nexo loan becomes $100,000 (principal) + $27.50 (daily interest day 2) + $27.51 (daily interest day 3) + $44.19 (daily interest day 4) = $100,099.20.
7. How can I get a discount on the interest rate
Thanks to our Low-Cost Credit Lines, you can benefit from reduced annual loan rates in the Platinum and Gold Loyalty tiers*, respectively, as long as the loan-to-value (LTV) ratio in your Credit Wallet remains below 20%.
*You must maintain a portfolio balance of at least $5,000 in value to access our Loyalty Program with its perks, including getting a discount on the loan interest rate.
Platinum:
- LTV below 20%: 1.9%
- LTV above 20%: 9.9%
Gold:
- LTV below 20%: 3.9%
- LTV above 20%: 11.9% or 12.9%, depending on your jurisdiction
Example:
Value of NEXO: 1,000 USD.
Total Portfolio Value, excluding NEXO: 10,000 USD.
Ratio of NEXO vs Rest of the Assets: 1,000 USD / 10,000 USD * 100 = 10%.
Loyalty Tier: Platinum.
Outstanding Loan: 500 xUSD.
Total Collateral Value in the Credit Wallet: 4,500 USD.
Credit Wallet LTV: 500 USD / 4,500 USD * 100 = 11%.
Your Credit wallet LTV is below 20%, and you are in the Platinum tier, so your loan rate is 1.9%.
8. Do Nexo loans have a maturity date
The standard maturity of a Nexo loan is one year. However, if you do not repay it by then, the loan will be automatically extended for another year (the number of such extensions shall be unlimited). Please note that the maturity date is reset every time you take out a new loan.
9. What are the specifics of my Nexo loan
There are no fixed monthly or quarterly payments. You can follow a repayment schedule that is most suitable for you and repay your loan partially or in full at your convenience.
A compound interest rate, determined by your Loyalty tier and your Portfolio Balance, is applied to the funds you withdraw from your Credit Line. To learn more about our loan rates, click here.
Note: In case you repay your Nexo loan within 45 days of the last withdrawal, the standard annual interest rate of 17.9% will be applied to the repaid amount for the remainder of the 45-day period, regardless of your current Loyalty Level. This information is also available on the Credit Line Repayment screen:

10. Can I take out more than one Nexo loan at a time
You can withdraw from your Available Credit Line as many times as you like, as long as you have enough collateral in your account to back the Nexo loan. When you request a new loan, crypto assets may be automatically transferred from the Savings Wallet to the Credit Wallet if the collateral in your Credit Wallet is insufficient to support the loan.
You can also split your borrowing into Separate Credit Lines - for example, dedicated credit lines for Nexo Booster and Nexo Card credit-mode purchases, each with its own collateral wallet. You can learn more here.
11. Do I have to pay tax on my Nexo loan or the crypto used as collateral
You may generally be required to pay a tax on your gain when, for instance, you sell an asset for a profit. Additionally, depending on your jurisdiction and the nature of the asset, borrowing against it might carry tax advantages compared to selling.
When considering any tax, financial, and accounting obligations, such reporting remains solely your responsibility as an individual customer. Nexo and its affiliates do not provide tax, legal, or accounting advice.
This article is not intended to provide such and should not be relied upon for tax, legal, and accounting advice. You should always consult your tax, legal, and accounting advisors before engaging in any transaction.
12. How is Nexo different from margin lending
Unlike margin trading, where the borrowed funds serve as collateral, you can use your Nexo crypto-backed loan for whatever purpose you like without having to lock the newly borrowed funds as collateral.
13. What are Separate Credit Lines and how do they work
Separate Credit Lines let you split your loans on Nexo into independently managed credit lines. Each credit line has its own collateral wallet, outstanding loan, interest, and repayment flow, so the activity of one product does not affect the others.
The available credit lines are:
- Classic: Your standard credit line, working as it does today. By default, all borrowing, Booster, and Nexo Card credit-mode activity stays here unless you open a dedicated line.
- Booster: A dedicated credit line for your Nexo Booster deals with its own collateral wallet.
- Nexo Card: A dedicated credit line for your Nexo Card purchases in Credit Mode, with its own collateral wallet.
- Zero-interest Credit: A separate, fixed-duration product with its own collateral wallet, shown alongside the other credit lines in the Credit Hub.
For Booster and Nexo Card, opening a dedicated credit line is optional — if you don't, that activity stays on your Classic credit line. Zero-interest Credit always operates on its own separate credit line.
Opening a dedicated credit line
Opening a dedicated Booster or Nexo Card credit line is optional. When you start a Booster deal or access the Nexo Card tab, you can choose to open a dedicated credit line for that product. You can also open one from the Credit Hub on the Nexo app or the Manage loans menu on the web platform. If you do not open a dedicated line, the transaction will be processed on your Classic credit line.
When you open a dedicated credit line, a new collateral wallet is created for it. You can then fund that wallet by transferring assets from your Savings Wallet.
What happens to my existing loans
Any outstanding loans you’ve had before Separate Credit Lines became available — including loans from Booster deals or Nexo Card purchases — remain on your Classic credit line. The separation applies only to new Booster deals and Nexo Card credit-mode transactions made after you open a dedicated credit line. You are not required to move or split existing loans.
Collateral wallets and transfers
Each credit line has its own collateral wallet. When you transfer assets, you choose which collateral wallet to move them into. Funds are transferred from your Savings Wallet to the chosen collateral wallet, and any excess collateral can be moved back to the Savings Wallet. Transfers between separate collateral wallets are unavailable.
Loan settings per credit line
Automatic collateral transfer, Fixed-term Savings unlock, and Low-interest borrowing are set separately for each credit line. Automatic collateral transfer and Fixed-term Savings unlock are also available for the Booster credit line. Low-interest borrowing is not available for the Booster credit line. None of the three settings applies to Zero-interest Credit. Learn more in How to manage your credit lines.
Repayments
When you make a repayment, you first choose which credit line you want to repay. You can then pick the repayment asset and the exact repayment amount.
Interest
Daily loan interest and any additional interest are independently calculated, tracked, and charged per credit line.
Automatic loan repayments and account restrictions
Automatic loan repayments apply to each credit line independently. If one credit line is undergoing automatic repayment, your other credit lines may still remain available to manage as long as they’re in good health. Some account functionalities might be unavailable while any automatic repayment is in progress.
Custom credit lines for Nexo Private clients
If you have an assigned relationship manager, you can request additional credit lines with terms negotiated by your relationship manager. These appear within your Classic credit line as separate Outstanding loan cards with their own Manage loan options.
14. How to manage your credit lines
Each credit line has its own settings that help you keep your loan healthy and manage borrowing costs. You can adjust them for each credit line separately in Credit line settings in the Nexo app or in Borrow settings on the Nexo platform. The three settings below work together. They are not available for Zero-interest Credit.
Automatic collateral transfer
When the value of your collateral drops, your LTV ratio rises. Automatic collateral transfer moves a portion of your crypto from the Savings Wallet (Flexible Savings) to the collateral wallet of that credit line to improve your loan health. The setting is on by default and creates an extra buffer against automatic loan repayments. Learn more in this article.
Fixed-term Savings unlock
Fixed-term Savings unlock is an optional setting that adds a second layer of support. If you are at risk of automatic loan repayments, Nexo can unlock assets held in Fixed-term Savings and move them to the collateral wallet of that credit line. This happens only after all available crypto in Flexible Savings has been transferred, and Automatic collateral transfer must be on for the same credit line. The interest accrued on an unlocked term is lost. Learn more in this article.
Low-interest borrowing
Low-interest borrowing is available to Gold and Platinum Loyalty Tier clients. It monitors the LTV ratio of your Credit Wallet and, if it goes above 20%, moves assets from Flexible Savings to keep it below that level. This setting requires Automatic collateral transfer to be on for the same credit line and is not available for the Booster credit line. Learn more in this article.
15. Important notes
- Interest is added to your outstanding balance daily at 00:00 UTC.
- The interest applied to loans is compound, i.e., it is calculated on both the initial principal and the accumulated interest.
- The minimum interest charge is 0.01 xUSD.
- Additional interest generated by making an early repayment is being added to your outstanding loan balance and, as such, cannot be repaid using NEXO tokens.
- Both SWIFT and Fedwire transfers are supported for loan withdrawals in USD. However, the availability of the Fedwire transfer method depends on your country of residence.
- When terms such as "up to" or "from" are used to denote limits, achieving these maximum or minimum thresholds may be conditional on additional actions or fulfilment of certain criteria and requirements that may not be attainable by all clients.